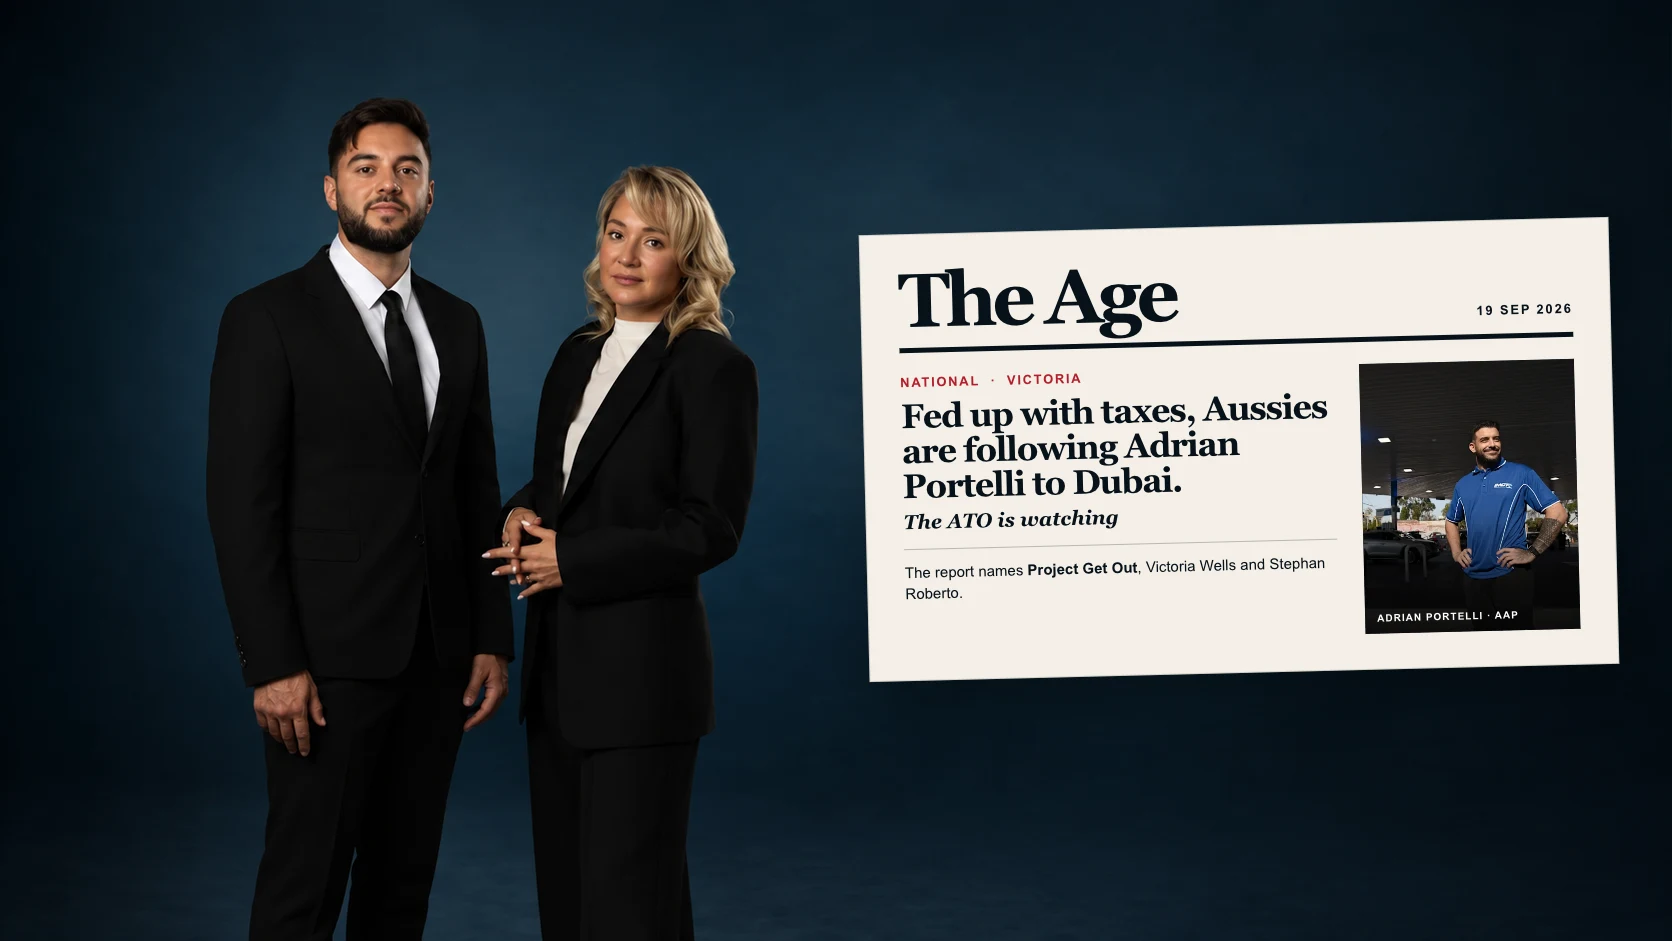
The Age has featured Project Get Out in its reporting on Australians considering a move to Dubai—and on the Australian Taxation Office scrutiny that can follow when the facts of an overseas move do not support the outcome a person expects.
The article names Project Get Out, Victoria Wells and Stephan Roberto. The practical answer for a reader considering Dubai is to examine personal tax residency, company residency and the location of business activity separately. A UAE visa does not settle the first question, moving a director does not automatically move an Australian-incorporated company, and selling to Australians does not by itself answer the third. The facts of the move matter more than the marketing shorthand.
Read the original article in The Age
The same report was also published by The Sydney Morning Herald and Brisbane Times. These links lead to editions of the same syndicated story, and a subscription may be required.
This article provides general information only. Tax, legal and immigration outcomes depend on individual facts and current law. Obtain advice from appropriately qualified professionals before acting.
At a glance
Key takeaways
- The Age named Project Get Out, Victoria Wells and Stephan Roberto in one report also carried by The Sydney Morning Herald and Brisbane Times.
- An overseas visa does not, by itself, settle an individual’s Australian tax residency.
- An Australian-incorporated company remains an Australian tax resident under the incorporation test even if its founder moves overseas.
- For a foreign-incorporated company, Australian customers alone do not settle corporate residency or the tax treatment of its income.
- A workable move needs the personal, family, business and destination facts to fit together.
What did The Age report about Project Get Out?
The Age reported that Project Get Out was launched to help Australians—particularly founders and people working in technology—understand the work involved in moving overseas.
The report also said Project Get Out received 1,000 enquiries shortly after launch and that Victoria was continuing to see about 200 enquiries a day at the time of the interview. Those figures are reported here as statements from The Age’s coverage, not as independently audited claims in this article.
More importantly, the article described Project Get Out as helping Australian founders, investors and high-net-worth families think about relocation and tax-residency issues. Victoria also told the reporter that the venture was not about engineering arrangements to avoid Australian tax. Our role is to help people see the complete move, identify the questions that need qualified advice and sequence the work coherently.
Why did we say tax should not be the whole decision?
Victoria told The Age that “tax should be one coordinate on the map, not the compass.”
That is the point we most want readers to keep.
Tax can be a legitimate consideration in a relocation decision. So can family, lifestyle, market access, regulation, housing, business operations, travel and the practical cost of establishing a new base. One attractive tax rate cannot tell you whether a destination will work for your life or whether your actual conduct will support the position you intend to take.
A better order is:
- decide what kind of life and business you are trying to build;
- compare destinations against those requirements;
- map the Australian, personal, business and destination-country questions separately;
- obtain advice from the right professionals for each question; and
- make sure the plan, the documents and what actually happens remain aligned.
What does the ATO warning in the article mean?
The coverage discusses tribunal cases involving Australians who lived overseas but disputed whether Australia still treated them as tax residents. The practical lesson is not that every Australian in Dubai remains an Australian tax resident. It is that residency is fact-dependent and cannot safely be reduced to a visa, day count, lease or stated intention.
The ATO’s own guidance says that tax residency is different from nationality or permanent-residency status and depends on the applicable residency tests and the person’s circumstances. ATO: your tax residency
Family arrangements, homes, travel, work, assets, business management and ongoing connections can all be relevant to the advice a person receives. Becoming a resident elsewhere also does not automatically end Australian tax residency.
That is why we separate three questions that are often collapsed into one:
- Do you have permission to live in the destination country?
- What is your tax-residency position in Australia and elsewhere?
- Where and how will your business actually operate?
A document that helps answer one question should not be treated as the answer to all three.
Does moving a company’s management to Dubai end Australian company tax residency?
The Age quoted Deakin Business School lecturer Dr Kerui Zhai observing that a company deriving much of its income from Australia would probably remain subject to Australian corporate tax. That warning is worth taking seriously, but customer location, company residency and whether particular income is taxable in Australia are different questions.
Start with incorporation. Under the Australian company-residency definition, a company incorporated in Australia is an Australian tax resident. Moving its founder, director or high-level decisions to Dubai does not, by itself, make that Australian-incorporated company cease to be an Australian resident. For a company incorporated outside Australia, the separate tests ask whether it carries on business in Australia and whether its central management and control is in Australia or its voting power is controlled by Australian-resident shareholders. The ATO explains those tests in Taxation Ruling TR 2018/5.
Central management and control means where high-level decisions that direct the company are actually made. Board minutes or an overseas registered office are evidence to examine, but the ATO focuses on what decision-makers really do and where they do it. The place where customers are located can matter to the wider tax analysis, but it does not answer this management question on its own. ATO: central management and control
| Situation | What can be said at the outset | What still needs advice? |
|---|---|---|
| Australian-incorporated company, founder now in Dubai | Australian incorporation itself satisfies the Australian company-residency test. | How Australian and foreign rules apply to its activities and income, including any relevant treaty or other relief. |
| Foreign-incorporated digital company serving Australian and overseas customers | Australian customers alone do not settle whether the company is Australian resident. | Where the business is carried on, who truly makes high-level decisions, voting control, Australian-source income, and any Australian presence. |
| Foreign-incorporated company with Australian premises and staff | The Australian operations require close analysis even if directors live abroad. | Company residency, source of income, permanent establishment, employment and GST obligations, and any applicable treaty. |
For a foreign-resident business, Australian tax obligations can also arise without Australian company residency. The ATO says the answer depends on the nature and scale of Australian activity, possible permanent establishment, and applicable tax treaties; GST and employment obligations can be separate again. ATO: foreign residents doing business in Australia
This is why a brick-and-mortar operation in Australia and a digital service selling globally should not be treated as the same fact pattern. Neither the amount of Australian revenue nor the location of a founder supplies a universal answer. A cross-border tax adviser needs the entity’s incorporation, ownership, people, decision-making, contracts and actual operations before reaching a conclusion.
Which questions should I take to an adviser?
Bring one fact file that distinguishes the person from every entity involved:
| Question | Evidence to gather |
|---|---|
| Where will I and my family actually live? | Homes, travel pattern, work location and continuing Australian ties. |
| Where was each company incorporated? | Registration records, entity chart and ownership details. |
| Who directs each company, and from where? | Actual decision-makers, meeting records and how significant decisions are made. |
| What work remains in Australia? | Staff, premises, contractors, customer delivery, assets and signing authority. |
| Where are customers, contracts and income connected? | Contract terms, service delivery and revenue by market. |
These facts give qualified advisers a usable starting point. They also expose gaps before anyone promises a particular tax result.
What should an Australian considering Dubai do next?
Do not start with the assumption that Dubai is right for you. Start by writing down what must be true for any move to work.
Consider:
- where you and your immediate family will genuinely live;
- what will happen to your Australian home and other ties;
- where you will perform and manage your work;
- which customers, contracts, assets and entities remain connected to Australia;
- what immigration status permits you to do in the destination;
- how banking, insurance, housing and everyday costs work in practice; and
- which decisions are reversible if the destination does not suit you.
Then bring the complete facts to appropriately qualified advisers. A coherent answer is more valuable than collecting isolated yes-or-no opinions from providers working from different assumptions.
What should I make of the three newspaper logos?
The Age, The Sydney Morning Herald and Brisbane Times published editions of the same syndicated report. The mastheads identify where readers can find it. They do not represent three separate interviews or an endorsement of Project Get Out. A subscription may be required to read an edition.
What the media coverage changes—and what it does not
We are grateful that The Age included Project Get Out in this national conversation. Independent coverage helps more Australians find the questions they need to ask before making a consequential move.
It does not turn a general article into personal advice. It does not make Dubai the right destination for everyone. And it does not change our central position: a proper move has to work as a real life and a real business, not merely on paper.
If you need the foundations, the Australian Exit Guide helps you organise the major planning areas before you act. If you want Project Get Out to understand your proposed move, you can complete the private fit check.
For a conclusion about your own tax, legal or immigration position, obtain advice from an appropriately qualified professional with the complete facts.
Important: This article is general information only and does not constitute legal, tax, financial, investment or immigration advice. Rules and programmes can change. Obtain advice from appropriately qualified professionals who understand your facts and the relevant jurisdictions before acting.